

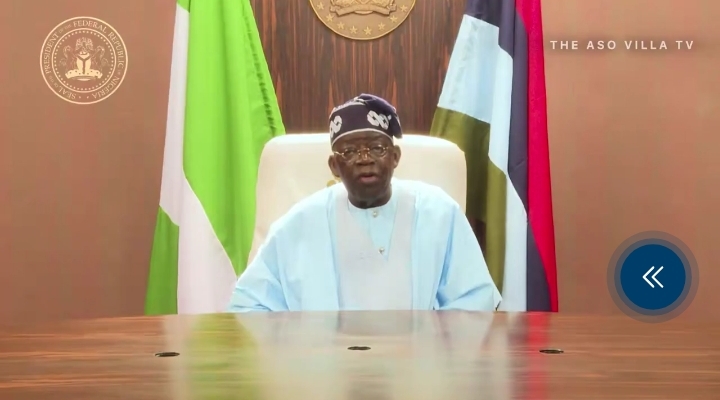
President Bola Tinubu has said Nigeria’s economic reforms are beginning to yield results, citing a new World Bank report that indicates economic growth has strengthened, poverty has stabilised and revenues available to state governments have increased.
The President, however, acknowledged that more work was needed to translate the reported economic improvements into better living conditions for Nigerians, particularly through lower food prices, job creation and improved access to essential services.
Tinubu stated this on Sunday while reacting to the World Bank’s October 2026 Nigeria Development Update, titled Beyond the Federal Purse: How Higher Revenues Reshaped State Priorities.
In a statement issued by his Special Adviser on Information and Strategy, Bayo Onanuga, the President described the report as further evidence that the administration’s economic policies were placing the country on a stronger footing for sustained growth.
According to the World Bank report, Nigeria’s economy grew by 4.2 per cent in the first half of 2026, compared with 3.9 per cent during the corresponding period in 2025, despite the impact of the conflict in the Middle East.
The bank projected that economic growth would average at least 4.4 per cent between 2026 and 2028.
It also reported that Nigeria’s poverty rate had stabilised for the first time since 2019, expressing expectations that poverty would gradually decline as economic growth outpaced population growth.
On inflation, the report showed that the rate fell from 27.6 per cent in January 2025 to 15.2 per cent in December 2025. However, higher global fuel prices associated with the Middle East conflict had slowed the subsequent decline.
The World Bank projected that inflation could ease to approximately 12 per cent by 2028.
Reacting to the findings, Tinubu said the government’s decisions to remove the petrol subsidy, unify the foreign exchange market and strengthen fiscal discipline had improved public revenues and created more resources for investment across the country.
“These findings confirm that the difficult but necessary decisions to remove the petrol subsidy, unify the foreign exchange market and strengthen fiscal discipline have raised revenues, stabilised the economy and created fiscal space for every tier of government to invest in its people,” the President said.
States’ revenues, capital spending rise
The World Bank report attributed a significant increase in government revenues to reforms introduced since 2023, stating that federation revenues rose by 69 per cent in real terms between 2023 and 2025.
State governments emerged as the largest beneficiaries of the additional revenue, with their capital expenditure increasing by 151 per cent in real terms over the same period.
The report said much of the additional spending went into roads and other transport infrastructure, agriculture, energy and housing.
It added that 29 of 33 states shifted their spending towards economic infrastructure, while real social spending per person increased in all but one state.
The bank also reported that internally generated revenue grew in real terms in 31 of 35 states, while 21 states reduced their debt-to-gross domestic product ratios between 2021 and 2025.
Nigeria’s overall public debt-to-GDP ratio was projected to decline from 40 per cent in 2025 to 38.1 per cent in 2026.
Tinubu said the reported improvements demonstrated the potential benefits of the reforms but stressed that economic gains must translate into tangible improvements in household welfare.
“The dividends of reform are becoming visible. But more work remains to ensure they fully translate into better living standards for every household, starting with lower food prices and decent jobs for our young people,” he said.
Tinubu promises more support for households
The President reaffirmed his administration’s commitment to sustaining the reforms while increasing attention to inclusive growth under its Renewed Hope Agenda.
He said the government would expand targeted cash transfers, accelerate the deployment of compressed natural gas, improve agricultural productivity and strengthen access to affordable healthcare and quality education.
According to him, the cash transfer programme has already reached more than 10 million households.
“Our administration will stay the course of reform and redouble its focus on inclusive growth under the Renewed Hope Agenda,” Tinubu said.
He added that the government would continue implementing measures aimed at ensuring that the benefits of economic growth reached more Nigerians.
“We will continue to expand targeted cash transfers, which have already reached more than 10 million households. We will accelerate the deployment of CNG, raise agricultural productivity, and improve access to affordable healthcare and quality education, so that the prosperity being created is shared by all,” he said.
The President also urged state governments to manage their increased revenues prudently and prioritise investments that would directly improve the welfare of residents.
“I urge state governments to use their higher revenues more prudently and prioritise projects that improve the living standards of Nigerians, and the health and education of our people,” he said.
External reserves rise to $53.8bn
The World Bank report also highlighted improvements in Nigeria’s external position, with the current account surplus rising to $12bn, representing 7 per cent of gross domestic product, in the first half of 2026.
The figure was higher than the $8.6bn recorded in the corresponding period of the previous year.
The country’s gross external reserves also increased from $45.5bn at the end of 2025 to $53.8bn at the end of August 2026.
Tinubu commended the Economic Management Team, led by the Minister of Finance and Coordinating Minister of the Economy, alongside state governors and other stakeholders, for their cooperation in implementing the reforms.
He assured Nigerians that his administration would continue pursuing policies aimed at improving economic stability and expanding opportunities.
“I assure Nigerians that the best is yet to come under the Renewed Hope Agenda 2.0, which will accelerate the delivery of shared prosperity for all Nigerians,” the President said.
The statement was signed by Onanuga and dated October 11, 2026.